Medicare Costs Decoded: What You’ll Really Pay in 2027
You’ve seen the ads. A smiling person on TV holding up a big sign: “$0 premium!” Is that what Medicare costs?
It sounds amazing. Free healthcare!
But then you talk to your neighbor. She has Medicare. She tells you she paid $8,000 last year for medical costs.
Wait, what? How can Medicare cost $8,000 if the premium is $0?
Here’s the truth: Medicare costs are confusing on purpose. Insurance companies know that if they just advertise the Medicare Advantage premium, it sounds cheap. But the premium is only one piece of what you’ll actually pay.
We spoke with Medicare expert Dalia Cabrera, who has 20 years of Medicare experience. She helped us break down what Medicare really costs so you can figure out which type of plan is right for you and what you’ll actually spend in 2027.
One note before we start: Medicare has confirmed the 2027 drug plan numbers, but the official Part A and Part B amounts usually come out in November. Where a number is still a projection from the Medicare Trustees, we say so. We will update this post when the final figures are published.
Watch >> Medicare Open Enrollment 2027: Understanding Your Options
First, Let’s Understand the Medicare Alphabet Soup
Before we talk about costs, you need to understand what Medicare actually is. Medicare isn’t one thing. It’s a federal program with several different parts that work together (or separately).
Think of Medicare like a cafeteria. You can choose different items to put on your tray. Some items you have to take. Others are optional. And there are two completely different ways to go through the line.
The Parts of Medicare
Part A (Hospital Insurance) covers hospital stays, skilled nursing facilities, hospice, and some home health care. Most people get Part A with no premium if they (or their spouse) worked and paid Medicare taxes for at least 10 years. Even with no premium, you still pay deductibles and coinsurance when you use it.
Part B (Medical Insurance) covers doctor visits, outpatient care, medical equipment, and preventive services. This is NOT free. In 2027, most people are projected to pay $209.50 per month. You also pay deductibles and 20% of the cost for most services, with no limit on how much you might pay.
Part C (Medicare Advantage) is the “all-in-one” alternative. Instead of separate Part A and Part B (and usually Part D), you get everything bundled through a private insurance company. These are the plans advertising “$0 premiums.” But you still pay the Part B premium to the government, plus co-pays when you use services.
Part D (Prescription Drug Coverage) covers medications. If you have Original Medicare (Parts A and B), you need to buy a separate Part D plan. If you have Medicare Advantage, drug coverage is usually included. Part D plans have their own monthly premiums, deductibles, and co-pays.
Two Different Paths: Original Medicare vs. Medicare Advantage
Here’s where it gets really confusing. You have two completely different ways to get your Medicare coverage.
Path 1: Original Medicare
- Premium: Part A is usually free. Part B is projected at $209.50 per month in 2027. If you have a higher income, you pay more.
- For Part A services, you pay a deductible per benefit period, then a daily copay for long stays
- For Part B services, Medicare pays 80% and you pay 20%, with no yearly limit, after the annual deductible
- You need a separate Part D plan if you want prescription coverage
- Many people also buy a Medigap plan to help pay their share of Part A and B costs
- You can go to any doctor or hospital that accepts Medicare (most do)
Path 2: Medicare Advantage (Part C)
- You still need Part A and Part B, and you still pay the Part B premium to the government
- A private company (like Humana or UnitedHealthcare) takes over your coverage
- You can only go to doctors in their network (except emergencies, urgent care, out-of-area dialysis, and plan-approved out-of-network care)
- You pay co-pays for services (like $25 for a doctor visit)
- Drug coverage is usually included
- There IS a yearly limit on what you pay, but it can be high. The federal ceiling for 2027 is $9,850 for in-network care.
What About Medigap?
If you choose Original Medicare, you might also want Medigap (also called Medicare Supplement Insurance). This is extra insurance that covers what Original Medicare doesn’t.
Medigap plans have letter names (like Plan G or Plan N). They cost extra, often $150 to $300+ per month. But they can save you thousands if you get sick.
Important: You can’t have both Medigap and Medicare Advantage. It’s one or the other.
Quick Summary: What Most People Have
Most people have one of these three setups:
1. Original Medicare + Part D + Medigap
- Most flexible (any Medicare-contracted doctor)
- Most expensive monthly premiums
- Part D covers prescription drugs
- Most predictable costs if you get sick
2. Original Medicare + Part D (no Medigap)
- Flexible (any Medicare-contracted doctor)
- Lower monthly costs
- Part D covers prescription drugs
- You are responsible for the 20% coinsurance. If you get really sick , you could pay a lot
3. Medicare Advantage
- Lower monthly premiums (sometimes $0 beyond Part B)
- Must use network doctors
- Usually pay copays – check the terms of your plan
- Protected by an out-of-pocket maximum
- Usually covers prescription drugs – check your specific plan
- Often includes extras like dental, vision or wellness
Now that you understand what Medicare actually is, let’s talk about what Medicare really costs.
The Four Types of Medicare Costs
Think of Medicare costs like a restaurant bill. You don’t just pay for your entree. You also pay tax, tip, and maybe an appetizer. Medicare works the same way.
There are four different types of costs.
1. Premiums (Your Monthly Bill)
This is what you pay every month just to have coverage. You pay it whether you go to the doctor or not. It’s like a membership fee.
For 2027:
- Part B premium: projected at $209.50 per month for most people (a 3.3% increase, much smaller than the 9.7% jump in 2026)
- Part D premium: varies by plan. Medicare says the average stand-alone drug plan premium is about $36 per month in 2027, and the national base premium is $41.33. But averages hide a lot. See the Part D section below.
- Medicare Advantage premium: can be $0, but might be $20, $50, or more depending on the plan. Medicare projects the average Medicare Advantage premium at $12 per month in 2027, down from $14.37.
- Medigap premium: varies widely, often $150 to $300+ per month depending on your age and location
2. Deductibles (What You Pay Before Coverage Kicks In)
The deductible is how much you pay first, before your insurance starts helping. Which deductibles you pay depends on which path you chose.
If you have Original Medicare, you pay up to three separate deductibles in 2027:
- Part A deductible: projected at $1,788 per benefit period (up from $1,736). You pay this when you are admitted to the hospital.
- Part B deductible: projected at $292 per year (up from $283). You pay this before Medicare starts paying for doctor visits and outpatient care.
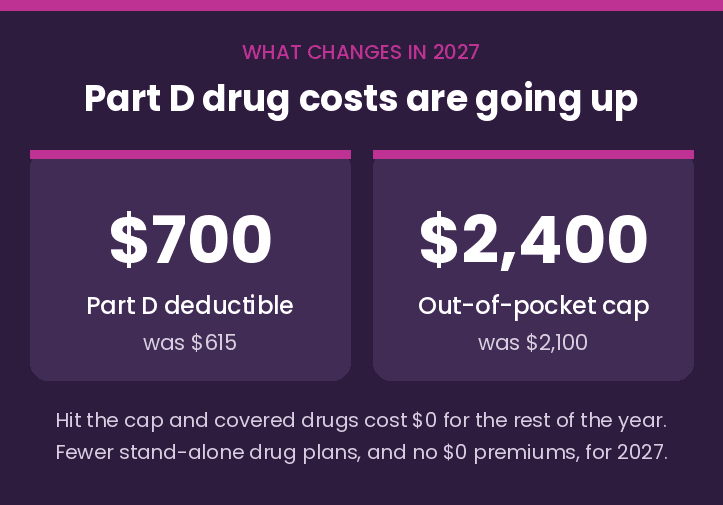
- Part D deductible: up to $700 per year (up from $615) on your stand-alone drug plan. Some plans charge less or $0. This number is final.
A Medigap plan may pay the Part A deductible for you. Only older Medigap plans (C and F) cover the Part B deductible, and new Medicare members cannot buy those.
If you have Medicare Advantage, the Part A and Part B deductibles do not apply. Instead, your plan sets its own rules. Many plans have no medical deductible and charge co-pays instead. Some have a plan deductible, and plans that include drug coverage may have a drug deductible of up to $700. Check the plan’s Summary of Benefits.
3. Coinsurance (Your Share After the Deductible)
Coinsurance is a percentage of the bill that you pay. This is mostly an Original Medicare cost.
If you have Original Medicare, Medicare pays 80% of most Part B services and you pay 20%, after the Part B deductible:
- You pay 20% of every doctor visit
- You pay 20% of every medical test
- You pay 20% of medical equipment
- There is NO LIMIT to how much you might pay
That last part is important. Say you need surgery that costs $50,000. Medicare pays 80%. You pay 20%. That’s $10,000 out of your pocket. A Medigap plan covers that 20% for you. Without Medigap, you are on the hook.
Part A also has a small coinsurance: you pay 5% of the cost of short-term respite care for a hospice patient.
If you have Medicare Advantage, most plans use flat co-pays instead of a percentage for routine care. But some services, like hospital outpatient procedures, durable medical equipment, or specialty drugs, may still charge coinsurance of 20% or more. The difference is that your plan’s out-of-pocket maximum caps the total.
4. Copays (Fixed Amounts for Certain Services)
A co-pay is a flat dollar amount for a service, like $15 for a doctor visit. Both paths have co-pays, but in different places.
If you have Original Medicare, co-pays show up mainly in the hospital and in your drug plan. Once you meet your Part A deductible for a hospital stay, days 1 through 60 cost $0 per day. Starting on day 61, you pay a daily copay ($434 per day in 2026; the 2027 amount will be announced in November). Skilled nursing facilities work the same way. Days 1 through 20 are $0. Starting on day 21, you pay a daily copay ($217 per day in 2026). Your Part D plan also charges a co-pay or coinsurance for each prescription. Review the Medicare Costs schedule for details.
If you have Medicare Advantage, co-pays are how you pay for almost everything: a flat amount for a primary care visit (often $0 to $25), a specialist visit (often $30 to $50), an emergency room visit, a hospital day, and each prescription. Every plan sets its own amounts, so two plans with the same $0 premium can have very different co-pays.
The Short Version
Original Medicare: Part A and Part B deductibles, then 20% coinsurance with no yearly limit. Most people add Medigap to cover the 20% and a Part D plan for drugs.
Medicare Advantage: No Part A or Part B deductible. Co-pays for each service, sometimes a plan deductible, and a yearly out-of-pocket maximum that caps what you pay for in-network care.
Both: You pay the Part B premium either way.
Here’s What Most People Don’t Realize About Medicare Costs
Original Medicare has NO yearly limit on what you can spend.
If you get very sick, you could spend $20,000, $30,000, or more in a single year on that 20% coinsurance. This is why many people buy Medigap to cover that 20%.
Medicare Advantage plans DO have a limit on what you spend each year. But that limit can be high. Many plans set it between $5,000 and $8,000, and federal rules allow up to $9,850 for in-network care in 2027.ys instead of coinsurance.
Here’s What Most People Don’t Realize About Medicare Costs
Original Medicare has NO yearly limit on what you can spend.
If you get very sick, you could spend $20,000, $30,000, or more in a single year on that 20% coinsurance. This is why many people buy Medigap to cover that 20%.
Medicare Advantage plans DO have a limit on what you spend each year. But that limit can be high. Many plans set it between $5,000 and $8,000, and federal rules allow up to $9,850 for in-network care in 2027.
Part D in 2027: Fewer Plans, No More $0 Premiums
Part D is a prescription plan if you elect to stay on Original Medicare. Most Medicare Advantage plans have prescriptions included (check your plan!). If you buy a stand-alone drug plan, 2027 is a year to look closely. Three things changed.
- Fewer plans. The number of stand-alone Part D plans drops about 13%, from 360 in 2026 to 312 in 2027, according to a KFF analysis of Medicare data. Your plan may not exist next year, or it may have merged into a different one.
- No $0-premium plans. For 2027, there are no stand-alone drug plans with a $0 premium for people who do not get Extra Help. Every stand-alone plan charges something.
- The subsidy is gone. In 2025 and 2026, Medicare paid insurers $9.8 billion to hold drug plan premiums down. Medicare ended that program for 2027. The average premium went up less than $1, but that average hides big differences. Some plans are going up a few dollars. Others are going up a lot.
The good news: Medicare says 88% of people can get a basic drug plan for $10.30 or less per month in 2027. But you have to look. The plan you have now may not be the cheap one anymore.
What You’ll Actually Pay: Real Comparisons of Medicare Costs
Let’s compare what the same person would pay with Original Medicare versus Medicare Advantage in 2027, using projected Part A and B amounts.
Robert: Managing Multiple Health Conditions
Robert is 72 with diabetes, heart disease, and arthritis. He sees his primary doctor monthly, three specialists quarterly, takes eight medications, and needs regular lab work. He had one hospital stay last year.
Option 1: Original Medicare (without Medigap)
Monthly costs:
- Part B premium: $209.50
- Part D premium: $45
- Total per month: $254.50
Yearly costs:
- Monthly premiums: $254.50 × 12 = $3,054
- Part B deductible: $292
- Doctor visits (20% of $200 each × 12): $480
- Specialist visits (20% of $300 each × 12): $720
- Lab tests (20% of $2,000 total): $400
- Part D medications: $2,400 (hits the cap)
- Hospital stay (Part A deductible): $1,788
- Hospital doctor fees (20% of $5,000): $1,000
- Total per year: $10,134
And remember: if Robert needs surgery or extensive treatment, there’s no limit to what he might pay.
Option 2: Medicare Advantage Plan
Monthly costs:
- Part B premium: $209.50
- Medicare Advantage premium: $25
- (Part D included)
- Total per month: $234.50
Yearly costs:
- Monthly premiums: $234.50 × 12 = $2,814
- Primary doctor co-pays: $15 × 12 = $180
- Specialist co-pays: $40 × 12 = $480
- Lab test co-pays: $20 × 6 = $120
- Medication co-pays: $1,800
- Hospital copay: $350 per day × 3 days = $1,050
- Total per year: $6,444
But here’s the key: this plan has a $6,700 out-of-pocket maximum. So even if Robert gets much sicker, that’s the most he’ll pay for covered services.
The verdict for Robert: Medicare Advantage saves him about $3,700 in a typical year AND protects him from unlimited costs if things get worse. The tradeoff? He must use network doctors.
Susan: Generally Healthy
Susan is 68 and in good health. She sees her doctor twice a year for checkups, takes two generic medications for blood pressure, and rarely needs other care.
Option 1: Original Medicare (without Medigap)
Monthly costs:
- Part B premium: $209.50
- Part D premium: $36
- Total per month: $245.50
Yearly costs:
- Monthly premiums: $245.50 × 12 = $2,946
- Part B deductible: $292
- Doctor visits (20% of $200 each × 2): $80
- Medication co-pays: $120
- Total per year: $3,438
But Susan worries: what if she breaks a hip or gets cancer? She could face tens of thousands in bills.
Option 2: Medicare Advantage Plan
Monthly costs:
- Part B premium: $209.50
- Medicare Advantage premium: $0
- (Part D included)
- Total per month: $209.50
Yearly costs:
- Monthly premiums: $209.50 × 12 = $2,514
- Doctor visit co-pays: $20 × 2 = $40
- Medication co-pays: $120
- Total per year: $2,674
This plan has a $5,500 out-of-pocket maximum, protecting Susan if she gets sick.
The verdict for Susan: Medicare Advantage saves her about $760 per year when healthy AND protects her with a spending cap. The downside? She must stay in network and might need referrals for specialists.
The Medigap Alternative
Both Robert and Susan could also consider Original Medicare WITH a Medigap plan. This would cost an extra $150 to $250 per month but would cover most or all of their share of Part A and Part B costs. For Robert, this could actually save money. For Susan, it’s expensive peace of mind.
What’s Changing for 2027
Costs going UP:
- Part B premium: projected up 3.3% to $209.50 per month
- Part A, Part B, and Part D deductibles all rising
- Part D out-of-pocket cap: rising from $2,100 to $2,400
- Stand-alone drug plan premiums: no more $0 plans, and some plans rising sharply now that the federal subsidy has ended
- Many Medicare Advantage plans: trimming extra benefits like dental and over-the-counter allowances
Costs going DOWN or holding steady:
- Average Medicare Advantage premium: projected to fall to $12 per month, and Medicare says about 8 in 10 Medicare Advantage members can keep their current plan at the same or a lower premium
- Fifteen more high-cost drugs get Medicare-negotiated prices starting January 1, 2027, on top of the 10 that started in 2026
- Insulin stays capped at $35 per month and recommended vaccines stay free
One more change to know about: more than a million people are losing their Medicare Advantage plan for 2027 as insurers pull out of markets. If you get a letter saying your plan is ending, read our guide on what to do when your Medicare Advantage plan is canceled.
The Truth About “$0 Premium” Plans
Let’s talk about those “$0 premium” Medicare Advantage plans.
They’re not lying. The plan’s premium really is $0.
But you still pay:
- The Part B premium to the federal government (most people have it taken out of their Social Security check)
- Copays every time you see a doctor
- Copays for medications
- Possibly higher costs if you go out of network
- Up to the plan’s out-of-pocket maximum if you get sick
A “$0 premium” plan is not the same as “$0 cost.”
As Dalia Cabrera, Umbra Medicare Patient Advocate, explains, “One common reason people should review new plans is if the renewal includes an increase on deductibles, co-payments, or coinsurance on medical services or prescription drugs when compared to what they had.”
How to Calculate What YOU Will Really Pay
Here’s how to figure out your actual costs for any plan:
Step 1: Add up all monthly premiums (Part B + Part D or Medicare Advantage + Medigap if you have it)
Step 2: Multiply by 12 to get your yearly premium cost
Step 3: Add your deductibles for the year
Step 4: Estimate your medical costs:
- How many doctor visits do you usually have?
- Do you see specialists?
- What do you pay per visit or per service?
- What do your medications cost with this plan?
Step 5: Add it all up
Step 6: Ask yourself: “What if I get sick? What’s the maximum I could pay?”
- With Original Medicare without Medigap, the answer is: there’s no maximum.
- With Medicare Advantage, look at the plan’s out-of-pocket maximum.
- With Original Medicare plus Medigap, you’re usually well protected.
The Hidden Medicare Costs People Forget
Don’t forget these costs that Medicare doesn’t cover:
- Dental care (cleanings, fillings, dentures)
- Routine vision care (eye exams, glasses)
- Hearing aids
- Long-term care (assisted living, nursing homes)
Some Medicare Advantage plans include some of these benefits. Original Medicare does not.
Why This Matters for Your Decision
Understanding costs helps you make a better choice.
Don’t just look at the premium. Look at the total picture.
A plan with a higher premium might actually cost you less overall if you use healthcare a lot. A plan with a $0 premium might end up costing you more if you have high co-pays and deductibles.
“The pros to enroll in a Medicare Advantage plan are that they offer additional benefits when compared to Original Medicare, at a low or no monthly premium, and the cost-sharing are lower,” says Dalia. “However, there are operational differences between private insurers, which influences the experience beneficiaries have with each one.”
This Is a Lot to Figure Out
Yes, it is. We know.
You’re trying to:
- Calculate premiums
- Add up deductibles
- Estimate co-pays and coinsurance
- Figure out medication costs
- Predict what might happen if you get sick
- Compare dozens of plans
It’s overwhelming. And you don’t have to do it alone.
Get Expert Help with the Math
Umbra’s Medicare advocates have 15 or more years of Medicare experience. Some have worked at CMS or inside a Medicare Advantage plan. They can help you calculate your real costs and choose the right plan.
An advocate can:
- Walk you through all four types of costs
- Help you calculate what you’d pay with different plans
- Show you how to use the Medicare Plan Finder tool
- Compare total yearly costs (not just premiums)
- Explain what you’d pay if you got sick
- Help you understand the fine print
If you already have Original Medicare, this support may be covered by Medicare. Call us at 332-699-6778 or tell us about your situation to see if you qualify.
Open enrollment ends December 7. Our advocates need about a week to compare plans with you, so reach out by November 30.
Don’t make a decision based on a TV commercial or fancy Medicare ads. Make a decision based on real numbers for your real life.