Medicare Advantage Plan Canceled for 2027? Get Your Complete Action Plan
You opened your mailbox and found a letter you weren’t expecting. Your insurance company is no longer offering your plan. The Medicare Advantage plan you relied on won’t be available starting January 1, 2027.
If this happened to you, you’re not alone. Now that Medicare has published its 2027 plan data, we know how big the shakeup is. Twelve insurers are leaving Medicare Advantage entirely, and 680 other plans are pulling out of at least one county. In all, at least one plan is leaving in 1,604 counties across 45 states. Humana alone is dropping plans that cover about 600,000 members. Rural counties are hit hardest, because there is often no comparable plan left to switch to.
This comes on top of 2026, when nearly 2.9 million people had to switch plans, about 10% of everyone on Medicare Advantage.
Don’t panic. You have options. And you have time to make a good choice.
We spoke with Dalia Cabrera, founder of Perseverance Patient Advocacy LLC and an Umbra Patient Advocate with 20 years of Medicare experience, to break down exactly what you need to know and do.
Why Is This Happening?
Healthcare costs are going up faster than what Medicare pays insurers. Insurance companies say they’re losing money on some plans, especially in rural areas. So they’re dropping those plans and focusing on markets where they can make a profit.
It’s frustrating. But the important thing now is understanding what happens next and what you need to do.
What That Letter Actually Means
Your letter probably says your plan “will not be available” or “is being discontinued” for 2027. By law, your insurer had to notify you by September 30. Here’s what that really means:
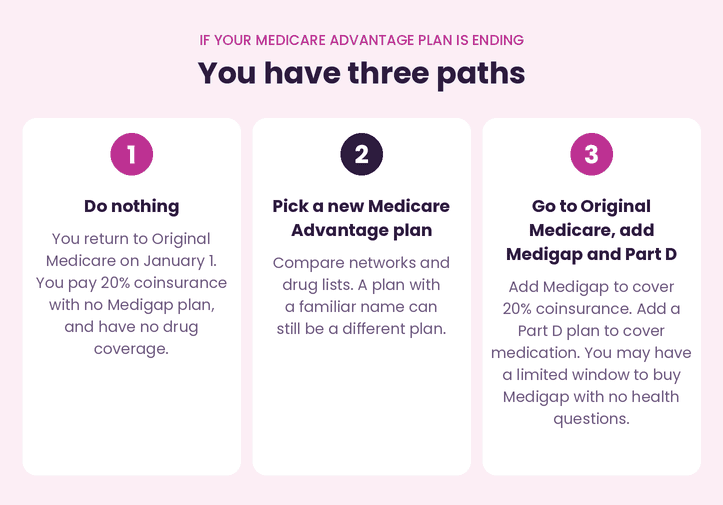
You will NOT be left without coverage. If you do nothing at all, you’ll automatically go back to Original Medicare on January 1, 2027. You’ll have Part A and Part B.
But here’s the catch: if you do nothing, you might not have prescription drug coverage (Part D) anymore. And you won’t have any extra benefits your Medicare Advantage plan included, like dental or vision. You’ll also be paying coinsurance or 20% of your medical costs with no yearly cap.
If you want to keep drug coverage and extra benefits, you need to make an active choice during Open Enrollment.
A Warning About “Quiet” Cancellations
Not every plan that’s going away gets a cancellation letter. Aetna, for example, stopped paying broker commissions on 123 plans across 33 states for 2027. Those plans technically still exist, but no agent will sell them, and they may shrink or disappear later. If your plan is still listed but your insurer seems to have stopped promoting it, read your Annual Notice of Change carefully and compare your options anyway.
Which Plans Are Leaving for 2027
Here is what the 2027 plan data shows. Your cancellation letter is the final word on your own plan, but this is the big picture.
The three big insurers
UnitedHealthcare, Aetna, and Humana account for about two of every three county exits. UnitedHealthcare is dropping 140 counties, Centene is dropping 344, and Elevance (Anthem) is dropping 56. Humana is trimming 57 counties but discontinuing plans that cover roughly 600,000 people. These companies are still selling plans in most places, so if your plan ended, there is probably another one from the same company or a competitor in your county. Compare it carefully. It may not have the same doctors, drugs, or benefits.
Insurers leaving Medicare Advantage completely
These companies will not sell individual Medicare Advantage plans anywhere in 2027. If your plan is from one of them, you need a new plan.
- Braven Health: all 21 New Jersey counties
- Wellmark Blue Cross Blue Shield: 98 Iowa counties and 43 South Dakota counties
- Blue Cross Blue Shield of North Dakota: all 53 North Dakota counties
- Blue Cross Blue Shield of Mississippi (Patrius Health): 26 Mississippi counties
- Christus Health Plan: 36 Texas counties and 8 New Mexico counties
- Aspirus Health Plan: 21 Wisconsin counties
- Providence Health Plan: 6 Oregon counties, 6 Washington counties, and Orange County, California
- WellSense Health Plan: all 10 New Hampshire counties
- Memorial Hermann Health Plan: 6 Texas counties
- Mass Advantage (UMass Memorial Health): Worcester County, Massachusetts
- Sharp Health Plan: San Diego County, California
- iCircle: a Dual Special Needs Plan in 14 New York counties
Molina, Horizon Blue Cross Blue Shield of New Jersey, Elderplan, and Presbyterian Health Plan are dropping their regular plans and keeping only Special Needs Plans, which are limited to people who also have Medicaid or certain chronic conditions.
Counties with no regular Medicare Advantage plan left
In 72 counties across 11 states, every regular Medicare Advantage plan with drug coverage is gone for 2027. Most of these are in North Dakota (21 counties), Minnesota (15), South Dakota (10), Oklahoma (7), Colorado (5), and Idaho (4), with a few in Montana, Nebraska, New Hampshire, California, and Utah.
In five counties there is no Medicare Advantage plan of any kind: Lake County, California; Custer, Hill, and McCone counties in Montana; and Coos County, New Hampshire.
If you live in one of these counties, Original Medicare is still there, and every one of these states has at least 8 stand-alone Part D drug plans to choose from. You also have special rights to buy a Medigap policy, which we explain below.
Your Three Options
You have three main paths forward.
Option 1: Choose a Different Medicare Advantage Plan
You can pick another Medicare Advantage plan in your area. Most people still have several plan options, though there may be fewer than last year.
This option might be right for you if:
- You like having dental, vision, and hearing benefits included
- You prefer lower monthly premiums, sometimes $0, and predictable copays
- Your doctors and hospitals are in the new plan’s network
- The new plan covers your medications
- You’re comfortable with requesting prior authorization before some treatments, knowing you may not always get it
What to watch out for:
- Make sure your doctors are in the new plan’s network. Insurers have been trimming networks, and some large health systems are dropping Medicare Advantage plans for 2027.
- Check that your medications are covered, and know what “covered” means. You may need prior authorization before the plan pays for a drug.
- Look at the plan’s Star Rating, a 5-point rating system where the best plans earn 5 stars.
- Compare extra benefits carefully. Many plans are cutting dental, vision, and over-the-counter allowances for 2027.
“The cons of enrolling in a Medicare Advantage plan are the limitations in the provider’s network,” explains Dalia Cabrera. “The enrollee can only use the providers contracted by the private insurer, not the nationwide providers contracted by Medicare.”
Option 2: Switch to Original Medicare Plus a Medigap Plan
You can go to Original Medicare and buy a Medigap policy. Medigap helps pay the 20% coinsurance for Medicare-covered services.
This option might be right for you if:
- You want to see any doctor who takes Medicare (no network restrictions)
- You have complex health needs or see specialists often
- You travel a lot and want coverage anywhere in the U.S.
- You can afford higher monthly premiums
Important timing note: Because your plan is ending, you have special “guaranteed issue rights.” This means Medigap companies MUST sell you a policy. They can’t say no because of your health. But this protection only lasts for a limited time, generally 63 days after your old coverage ends. Don’t wait.
What to watch out for:
- Medigap policies can have high monthly premiums
- You’ll need to add a separate Part D plan for prescription coverage
- The combination can cost more each month than Medicare Advantage, but you might get more coverage for what you need
Option 3: Original Medicare Plus a Part D Plan (Without Medigap)
You can go to Original Medicare and add a stand-alone Part D prescription drug plan. You skip the Medigap policy.
This might be right for you if:
- You’re generally healthy and don’t go to the doctor often
- You want flexibility to see any Medicare doctor
- You want to keep monthly costs lower
What to watch out for:
- Original Medicare has no limit on what you pay out of pocket each year. If you get very sick, your costs could be high. You pay 20% of every doctor visit and medical service.
- You’ll pay a monthly Part D premium while some Medicare Advantage plans offer low or no premiums
- Original Medicare doesn’t cover dental or vision
- Avoid the Part D late enrollment penalty. It applies if you go 63 days or more without creditable drug coverage.
What 2027 Costs Look Like
Whichever path you choose, here’s what to budget for in 2027:
- Part B premium: projected at $209.50 per month (CMS confirms the final number in November)
- Part B deductible: projected at $292
- Part A hospital deductible: projected at $1,788
- Part D out-of-pocket cap: $2,400
- Part D standard deductible: up to $700
For a full breakdown, read Medicare Costs Decoded: What You’ll Really Pay in 2027.
Your Action Plan: What to Do Now
Here’s exactly what to do, step by step.
Step 1: Find your termination letter and read it carefully. Note the date your current plan ends.
Step 2: Make a list of:
- All the medications you take (with dosages, formulation, and brand, if any)
- All your doctors’ names
- Any medical procedures you know or think you’ll need in 2027
Step 3: Think about what matters most to you:
- Do you need to keep seeing specific doctors?
- Do you want dental or vision benefits?
- How much can you afford to pay each month?
- Do you travel often?
- Do you care about flexibility in what services you get and where?
Step 4: Compare your options using the Medicare Plan Finder at Medicare.gov. 2027 plan details are available there starting October 1.
Pro tip: If you create an account or log in, the tool will automatically load your current medications. To create an account, you just need your Medicare ID, name, and date of birth. This saves you time entering everything manually.
Step 5: Look at Star Ratings. Plans with 4 or 5 stars are considered the best quality and usually have happier members.
Step 6: If you’re thinking about Medigap, call companies NOW to get quotes. They have to sell you a policy because your plan is ending, but your rights won’t last forever.
Step 7: Make your choice and enroll. Don’t wait until the end of Open Enrollment (December 7). Things can go wrong at the last minute.
Important Deadlines
- October 15 to December 7, 2026: This is the Annual Enrollment Period. You MUST make your choice during these dates. Everyone on Medicare can enroll, disenroll, or change plans during this window.
- January 1 to March 31, 2027: This is the Medicare Advantage Open Enrollment Period. It’s only for people already in a Medicare Advantage plan. It’s one more chance to switch to a different Medicare Advantage plan or go to Original Medicare. But it’s better not to wait.
One more window if your plan is leaving: People whose plan is leaving their county get a special enrollment period from December 8, 2026 to February 28, 2027. But a plan you pick in January doesn’t start until February 1, and one picked in February starts March 1. Choose by December 7 so your coverage starts January 1.
What If You Miss the Deadline?
If you don’t enroll in a new plan by December 7, you’ll automatically go back to Original Medicare on January 1. You won’t have drug coverage unless you add a Part D plan.
Missing the deadline means you might face gaps in coverage. You might also face a penalty for enrolling in Part D late. Don’t let this happen.
A Note About Those “New Plan” Letters
Some insurance companies send two types of letters. One says your plan is ending. Another might offer you a “replacement plan” to switch to automatically.
Be careful. Just because the company offers you a specific replacement plan doesn’t mean it’s the best choice for you. They’re choosing what works for them, not necessarily what works for you.
Compare that replacement plan against all your other options. Make sure it truly fits your needs.
This Is Confusing, and That’s Okay
Let’s be honest: Medicare is complicated. Having your plan canceled makes it even more stressful. You might feel overwhelmed. That’s completely normal.
You Don’t Have to Figure This Out Alone
Umbra’s Medicare advocates have deep Medicare experience. Some have worked at CMS or inside a Medicare Advantage plan. They can help you navigate this situation.
Here’s what an advocate can do for you:
- Review your termination letter and explain what it means
- Help you compare all available plans in your area
- Check if your doctors are in network for different plans
- Walk you through the Plan Finder tool and calculate real costs
- Explain the differences between Medicare Advantage and Original Medicare
- Help you understand Medigap options and guaranteed issue rights
- Walk you through the enrollment process step by step
Whether you need a different Medicare Advantage plan, want to move to Original Medicare and add a Medigap policy, or just need a stand-alone Part D plan, an Umbra advocate can walk you through it and help you enroll.
If you already have Original Medicare Part B, this support may be covered by Medicare. Call us at 332-699-6778 or tell us about your situation to see if you qualify.
Don’t make this important decision alone. Get help from a Medicare expert.